What is the baseline market scope and valuation of the Electric Mining Equipment Market?
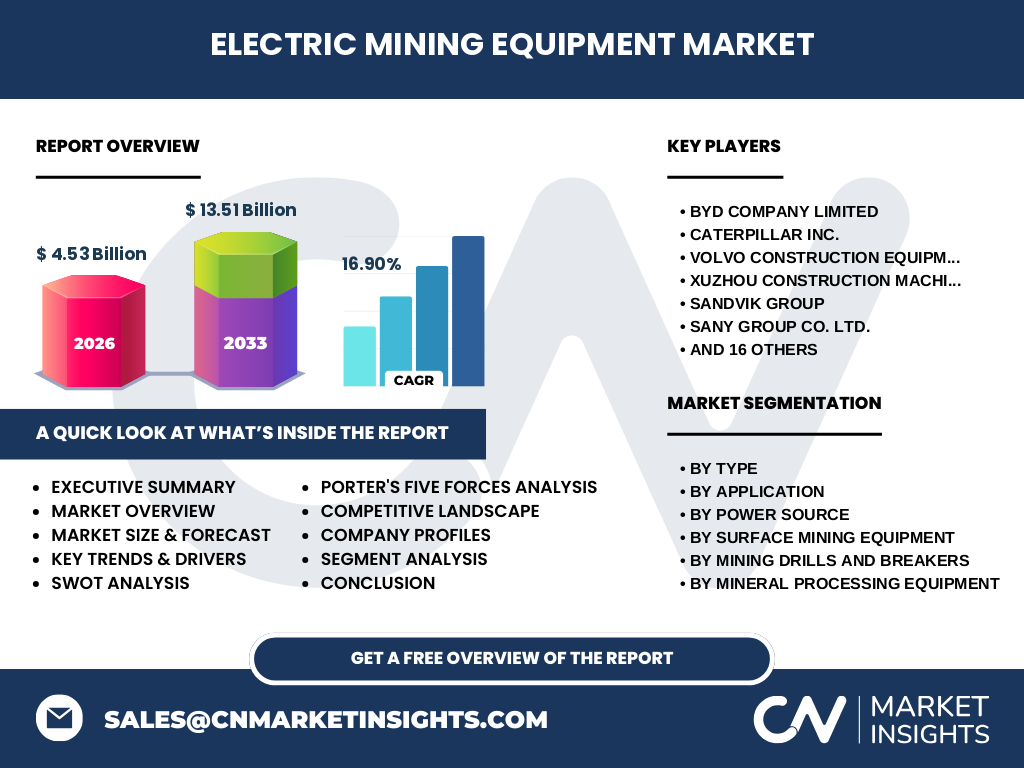
Our analysis indicates that the Electric Mining Equipment Market size stands at 4.53 Billion in 2026. This valuation encompasses heavy machinery deployed across surface and underground extraction sites to reduce diesel particulate matter (DPM) emissions and optimize ventilation underground.
Structural Growth Drivers and Restraints in the Electric Mining Equipment Market
The market is propelled by strict MSHA and EU diesel emission standards, yet constrained by severe grid capacity limits at remote extraction sites. Caterpillar Inc. and Komatsu Ltd. are addressing these infrastructure hurdles through modular megawatt charging stations.
Emerging Technological Shifts in the Electric Mining Equipment Market
The transition toward battery-electric equipment and fuel cell–based electric equipment is accelerating as mines target net-zero carbon pledges. Epiroc AB and Sandvik Group lead this shift by deploying high-density lithium-ion battery packs tailored for grueling duty cycles.
Pandemic Recovery Trajectory and COVID-19 Impact
Global supply chain disruptions during COVID-19 delayed electrification rollouts, but subsequent ESG capital mandates triggered a sharp rebound. Mining houses accelerated automation and remote-control fleet purchases to insulate operations against future labor shortages.
Competitive Benchmarking and Market Concentration
The Electric Mining Equipment Market industry trends show high consolidation among Tier-1 OEMs like Liebherr-International Deutschland GmbH, SANY Group Co. Ltd., and Hitachi Construction Machinery Co. Ltd. These giants leverage massive R&D budgets to dominate surface and underground electrification.
Executive Summary of High-Level Findings
Our comprehensive Electric Mining Equipment Market analysis reveals a robust expansion trajectory driven by strict environmental mandates and total cost of ownership advantages. Strategic electrification is no longer optional for major miners operating deep underground veins.
Long-Term Revenue Projections for the Electric Mining Equipment Market
Driven by a stellar compound annual growth rate of 16.90%, the Electric Mining Equipment Market forecast projects revenue to surge from 4.53 Billion in 2026 to 13.51 Billion by 2033. This exponential scaling reflects widespread commercial fleet replacements.
Comprehensive Segmentation Breakdown of the Industry
Our Electric Mining Equipment Market research segments the landscape by type, application, and power source. Key categories include mineral processing equipment, surface mining equipment, underground mining equipment, mining drills and breakers, alongside specialized crushing, pulverizing, and screening equipment.
Geographic Distribution and Regional Performance Dynamics
Regional adoption varies significantly, with Nordic countries leading underground electrification due to carbon taxes, while Latin American open-pit copper mines prioritize massive haul truck efficiency. Suppliers like Normet Group and MacLean Engineering capture substantial regional market share.
In-Depth Regional Review Across Major Mineral Basins
North American and Australian operations are spearheading tethered electric and battery-electric equipment deployments to curb ventilation operating expenses. Strict localized air quality regulations in these jurisdictions compel mine operators to phase out older diesel fleets rapidly.
Strategic Positioning of Leading Industry Participants
Market leaders utilize distinct maneuvers: Volvo Construction Equipment AB and Xuzhou Construction Machinery Group Co. Ltd. focus on mid-sized electric loaders, while niche innovators like Artisan Vehicle Systems Inc., Rokion, and Miller Technology Inc. supply specialized utility vehicles.
Porter's Five Forces Assessment of Competitive Pressures
Supplier power remains moderate due to specialized battery chemistry demands, while buyer power is high among mega-miners demanding bespoke fleet solutions. Threat of substitutes is low given the unique torque and safety requirements of deep subterranean extraction environments.
SWOT Matrix of the Sector
Key strengths include zero DPM emissions and lower noise profiles, offset by weaknesses in initial capital expenditure. Opportunities lie in autonomous battery-swapping infrastructure, while threats stem from critical mineral supply chain bottlenecks for lithium and cobalt.
Value Chain Analysis from Raw Materials to End-Users
The value chain flows from battery mineral refiners and semiconductor foundries to OEM assembly plants operated by firms like Belarusian Autoworks and AARD Mining Equipment. Final delivery runs through specialized logistics networks directly to active pit and shaft sites.
Strategic Investment Insights and High-Potential Areas
Investors should target developers of solid-state battery cells and fast-charging grid integration systems. Firms providing retrofit kits for legacy diesel machinery—such as Ampcontrol and Kress Corporation—represent high-potential acquisition targets.
Conclusion and Definitive Industry Takeaways
The Electric Mining Equipment Market growth trajectory is irreversible. Operators failing to electrify face severe regulatory penalties and higher long-term operating costs, making fleet modernization an absolute prerequisite for future operational viability.
Proprietary Research Methodology and Triangulation Framework
Our baseline estimates are rigorously triangulated by combining customs trade registries, primary executive interviews with Wacker Neuson SE and Doosan Infracore Co. Ltd. stakeholders, and secondary macroeconomic indicators from global mining councils.
Scope of the Report and Analytical Parameters
This report covers global revenue streams from 2026 through 2033, analyzing OEM production volumes, battery capacities, and regional regulatory compliance costs. Limitations exclude artisanal small-scale mining operations lacking formal capital equipment budgets.
Recent Corporate Developments and Strategic Partnerships
Recent months saw aggressive joint ventures between major equipment manufacturers and battery technology startups. Strategic product launches focusing on autonomous electric dump trucks highlight the industry's race toward fully unmanned, zero-emission extraction operations.